Envision Funding

We Close Loans Fast!

  • Home
  • About
    • About Us
    • Privacy Policy
  • Blog
  • Resources
    • First Time Home Buyer Tips
    • First Time Home Seller Tips
    • Closing Costs
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage FAQ
    • Mortgage Glossary
    • Debt Solutions
  • Applications
    • Apply Now Short Form
    • Business Funding Full Application
    • Broker Registration
    • Real Estate Lending Quick Application
  • Loan Programs
    • Business Loans
    • Commercial Loans
  • Contact

How Mortgage Underwriting Looks at Your Financial Picture

September 11, 2026 by Regine Lane

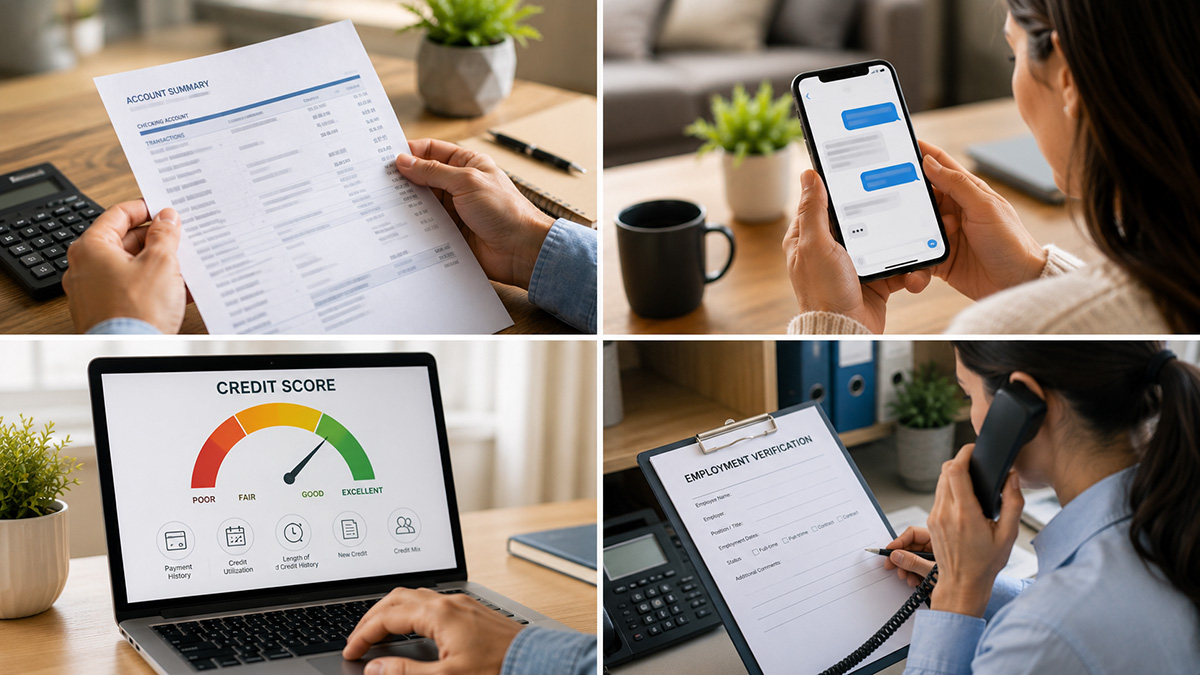
Mortgage underwriting can seem mysterious when you are buying a home. You submit documents, answer questions, and sometimes receive requests for additional information without knowing exactly what is happening behind the scenes. Understanding the purpose of underwriting can make this stage of the mortgage process much less intimidating.

Underwriting Looks Beyond One Number
A mortgage decision is generally not based solely on your credit score or income. Underwriting evaluates multiple parts of your financial profile to determine whether the loan meets applicable lending requirements.
The exact criteria depend on the mortgage program and lender.

Income and Employment Are Reviewed
Lenders need to document qualifying income and may review employment history and the way you are compensated.

Salary, hourly wages, commissions, bonuses, self-employment income, and other income sources may have different documentation requirements.

Credit and Monthly Obligations Matter
Your credit history can provide information about how you have managed financial obligations. Underwriting may also consider debts such as auto loans, student loans, credit cards, and other required monthly payments. These obligations can affect the amount of mortgage debt you qualify to carry.

Assets May Need Documentation
Funds used for the down payment, closing costs, and applicable reserve requirements may need to be verified.

Large or unusual deposits can sometimes generate questions because the lender may need to document where the money originated. Before moving significant amounts of money between accounts during the mortgage process, consider discussing it with your mortgage professional.

The Property Is Part of the Equation
Underwriting is not only about the borrower. The property securing the mortgage must also satisfy requirements associated with the loan. An appraisal and other documentation may be used to evaluate aspects of the property and transaction.

Additional Questions Are Not Unusual
A request for another document does not automatically mean something is wrong. Underwriters may simply need additional information to complete the file.

Underwriting is ultimately about putting the pieces of your financial picture together. Staying organized, responding promptly to documentation requests, and avoiding unnecessary financial changes can help keep the process moving toward closing.
Filed Under: Mortgage Tips Tagged With: Home Loans, Mortgage Tips, Mortgage Underwriting

What Underwriters Look For in the Final Weeks Before Closing

June 19, 2026 by Regine Lane

Many home buyers assume the hard work is finished once their mortgage application has been approved. However, the final weeks before closing are an important stage of the process. During this time, underwriters continue reviewing information to ensure everything remains consistent with the details originally provided. Understanding what they look for can help you avoid last-minute surprises.

Employment Verification Remains Important
One of the final checks that lenders perform is verifying employment. In many cases, employers are contacted shortly before closing to confirm that the borrower is still actively employed. If there has been a recent job change, additional documentation may be required. Maintaining open communication with your lender is essential if your employment situation changes.

Bank Accounts Are Carefully Reviewed
Underwriters may review updated bank statements to verify that funds needed for closing are available. They also look for unusual deposits that may require documentation. If large sums of money appear in an account, borrowers may be asked to explain where the funds came from and provide supporting records.

Credit Activity Can Trigger Questions
Many lenders perform a final credit review before closing. New credit accounts, increased balances, or large purchases can affect debt obligations and potentially impact loan qualification. Buyers should avoid financing furniture, vehicles, or other major purchases until after the transaction has been completed.

Documentation Must Remain Consistent
Underwriters compare updated information against the original application. Any discrepancies may require clarification. Consistency helps demonstrate financial stability and reduces the likelihood of delays. Keeping organized records and responding promptly to requests can make this process much easier.

Communication Helps Prevent Delays
The final weeks before closing often move quickly. Buyers who respond promptly to lender requests can help keep the transaction on schedule. Waiting several days to provide documents may create avoidable delays, especially when closing dates are approaching.

Focus on Reaching the Finish Line
The final review process is designed to protect both the lender and the borrower by ensuring all information remains accurate. While additional requests can feel inconvenient, they are a normal part of the mortgage process. Staying financially stable, avoiding major changes, and maintaining communication with your lender can help ensure a smooth path to closing day.

Filed Under: Mortgage Tips Tagged With: Closing Day, Mortgage Tips, Mortgage Underwriting

Envision Funding
Private Money Lender
Call Today: 678-719-9669

Connect with Us!

Let’s Keep In Touch!

  • This field is for validation purposes and should be left unchanged.

Browse Articles by Category

The Latest Articles

  • How Buying a Home With Someone You Are Not Married To Changes the Financial Conversation
  • What Happens to Your Mortgage Options When a Home Does Not Appraise as Expected?
  • Why the Type of Property You Buy Can Affect Your Mortgage Options
  • What’s Ahead For Mortgage Rates This Week – September 14th, 2026
nmlsconsumeraccess.org
Equal Housing Lender

Envision Funding Solutions, Real Estate Loans, Kennesaw, GA

Our Location

Envision Funding Solutions LLC
3104 Creekside Village Dr, Ste 507 Kennesaw, GA 30144

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in