Envision Funding

We Close Loans Fast!

  • Home
  • About
    • About Us
    • Privacy Policy
  • Blog
  • Resources
    • First Time Home Buyer Tips
    • First Time Home Seller Tips
    • Closing Costs
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage FAQ
    • Mortgage Glossary
    • Debt Solutions
  • Applications
    • Apply Now Short Form
    • Business Funding Full Application
    • Broker Registration
    • Real Estate Lending Quick Application
  • Loan Programs
    • Business Loans
    • Commercial Loans
  • Contact
Block
Envision Funding Solutions
We are here for your business and family needs.
Now offering residential mortgages!
Schedule a Consultation
home icon
Interested in Purchasing a Home?
Fill out this form and we'll be in touch
Refinance icon
Interested in Refinancing?
Fill out this form and we'll be in touch
calculator
Get a Rate Quote
Want a quick quote? Fill out this form
Application
Business Funding Full Application
Ready to get started? Click here!

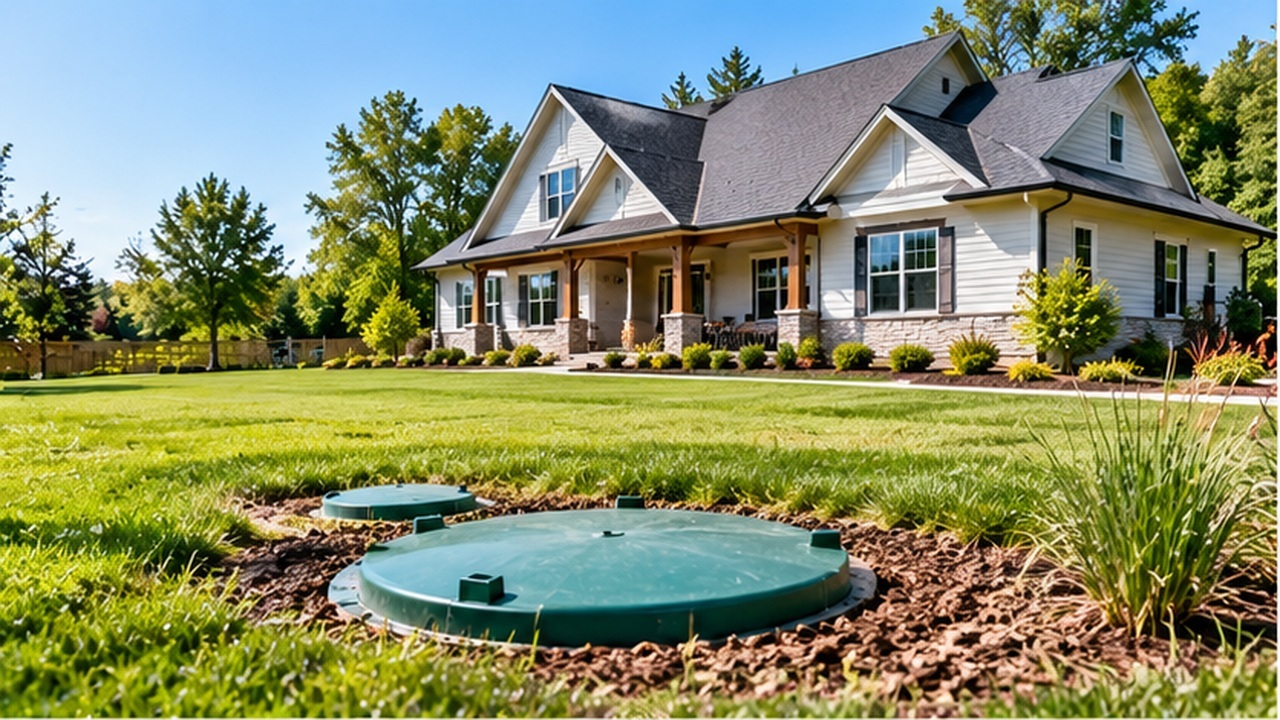
Why a Home With a Shared Septic System Can Complicate Mortgage Financing

October 13, 2026 by Regine Lane

A home can look perfect during a showing, but certain features of the property may create questions when it comes time to secure a mortgage. One situation buyers may not anticipate is purchasing a home that shares a septic system with another property.

While shared systems can function effectively, they may require additional documentation and review before financing can move forward.

Understanding How a Shared Septic System Works
Most buyers are familiar with homes that connect to a public sewer system or have their own private septic tank. However, some properties share a wastewater treatment system with one or more neighboring homes.

This arrangement may have been established when the properties were originally developed or when land was divided into separate parcels. Although each home has its own plumbing, wastewater from multiple properties may flow into a common treatment system.

The important question is not simply whether the system works. Buyers also need to understand who owns it, who maintains it, and how responsibilities are divided.

Why Lenders May Request Additional Information
Mortgage lenders evaluate more than the buyer’s income and credit history. They also review the property to determine whether it meets the requirements of the loan program.

When a septic system is shared, the lender may need documentation establishing the legal right to use the system. Depending on the loan program and circumstances, this could include recorded agreements, easements, maintenance provisions, or other property records.

The lender may also need confirmation that the system meets applicable health and safety requirements.

Requirements vary by mortgage program, so buyers should not assume that every shared system will create the same financing challenges.

Who Pays When Something Goes Wrong?

A shared septic system creates an important financial question: What happens when repairs are needed?

If the tank requires pumping, a drain field fails, or the system needs replacement, the cost may be shared among participating property owners.

A written agreement can help establish how expenses are divided, who arranges maintenance, and what happens if one owner refuses to contribute.

Without clear arrangements, buyers could face unexpected disagreements or expenses after purchasing the property.

Ask Questions Before Making an Offer

Buyers considering a home with a shared septic system should request available agreements, maintenance records, inspection information, and details about participating properties.

They should also discuss the arrangement with their mortgage professional early in the process rather than waiting until underwriting begins.

A shared septic system does not automatically prevent someone from obtaining a mortgage. However, understanding the property’s legal and maintenance arrangements before making a purchase can help buyers avoid surprises, evaluate future responsibilities, and move through the financing process with greater confidence.
Filed Under: Mortgage Tips Tagged With: Home Buyer Tips, Mortgage Financing, Septic Systems

What’s Ahead For Mortgage Rates This Week – October 12th, 2026

October 12, 2026 by Regine Lane

The FOMC Minutes and Consumer Sentiment report were the most impactful calendar items last week, further reinforcing the Federal Reserve’s resolve to bring inflation down to its 2% target rate.

While there is considerable speculation about another rate increase, recent analyst expectations suggest that the Fed will hold rates at their current level for some time. The Consumer Sentiment report showed a slight increase, largely driven by moderating gas prices, which have helped provide consumers with some relief.

Consumer Sentiment Report
The University of Michigan Consumer Sentiment index was revised higher to 49.5 in June 2026, up from a preliminary reading of 48.9, although it remained slightly below forecasts of 50. Still, sentiment improved from 44.8 in May, the lowest level on record, supported in part by a moderation in gasoline prices. The expectations gauge was at 50.7, the highest in three months, compared to 49.3 in the initial estimate, as consumers’ worries over long-term consequences of the Iran conflict appear to be easing.

FOMC Minutes
The Fed chief reiterated that the central bank will no longer provide traditional forward guidance on future interest-rate decisions, signaling a shift in its communication approach. Inflation risks have eased in recent weeks, but the US central bank remains committed to restoring inflation to its 2% target, Federal Reserve Chair Kevin Warsh said at the ECB’s Sintra Forum. Warsh stressed that delivering price stability remains the Fed’s primary objective, while underscoring policymakers’ independence in setting monetary policy and rejecting any suggestion that political pressure would influence their decisions.

Primary Mortgage Market Survey Index

  • 15-Year FRM rates saw an increase of 0.13%, bringing the current rate to 6.73%.
  • 30-Year FRM rates saw an increase of 0.12%, bringing the current rate to 7.40%.

MND Rate Index

  • 30-Year FHA rates saw a decrease of -0.05%, with current the rate at 7.15%.
  • 30-Year VA rates saw a decrease of -0.04%, with current the rate at 7.17%.

Jobless Claims
Initial Claims were reported to be 197,000 compared to the expected claims of 200,000. The previous week landed at 199,000.

What’s Ahead
Next week brings a full economic calendar, including the CPI and PPI inflation data releases, retail sales, and the increasingly impactful 5- and 10-year Treasury note auctions.

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

  • 1
  • 2
  • 3
  • …
  • 1001
  • Next Page »

Envision Funding
Private Money Lender
Call Today: 678-719-9669

Connect with Us!

Let’s Keep In Touch!

  • This field is for validation purposes and should be left unchanged.

Browse Articles by Category

The Latest Articles

  • Why a Home With a Shared Septic System Can Complicate Mortgage Financing
  • What’s Ahead For Mortgage Rates This Week – October 12th, 2026
  • Why Buying a Home From a Family Member Can Make the Mortgage More Complicated
  • What Happens to Your Mortgage When the Home Has an Unfinished Addition?
nmlsconsumeraccess.org
Equal Housing Lender

Envision Funding Solutions, Real Estate Loans, Kennesaw, GA

Our Location

Envision Funding Solutions LLC
3104 Creekside Village Dr, Ste 507 Kennesaw, GA 30144

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in