Envision Funding

We Close Loans Fast!

  • Home
  • About
    • About Us
    • Privacy Policy
  • Blog
  • Resources
    • First Time Home Buyer Tips
    • First Time Home Seller Tips
    • Closing Costs
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage FAQ
    • Mortgage Glossary
    • Debt Solutions
  • Applications
    • Apply Now Short Form
    • Business Funding Full Application
    • Broker Registration
    • Real Estate Lending Quick Application
  • Loan Programs
    • Business Loans
    • Commercial Loans
  • Contact

How Mortgage Payments Change Over the Life of Your Loan

August 14, 2026 by Regine Lane

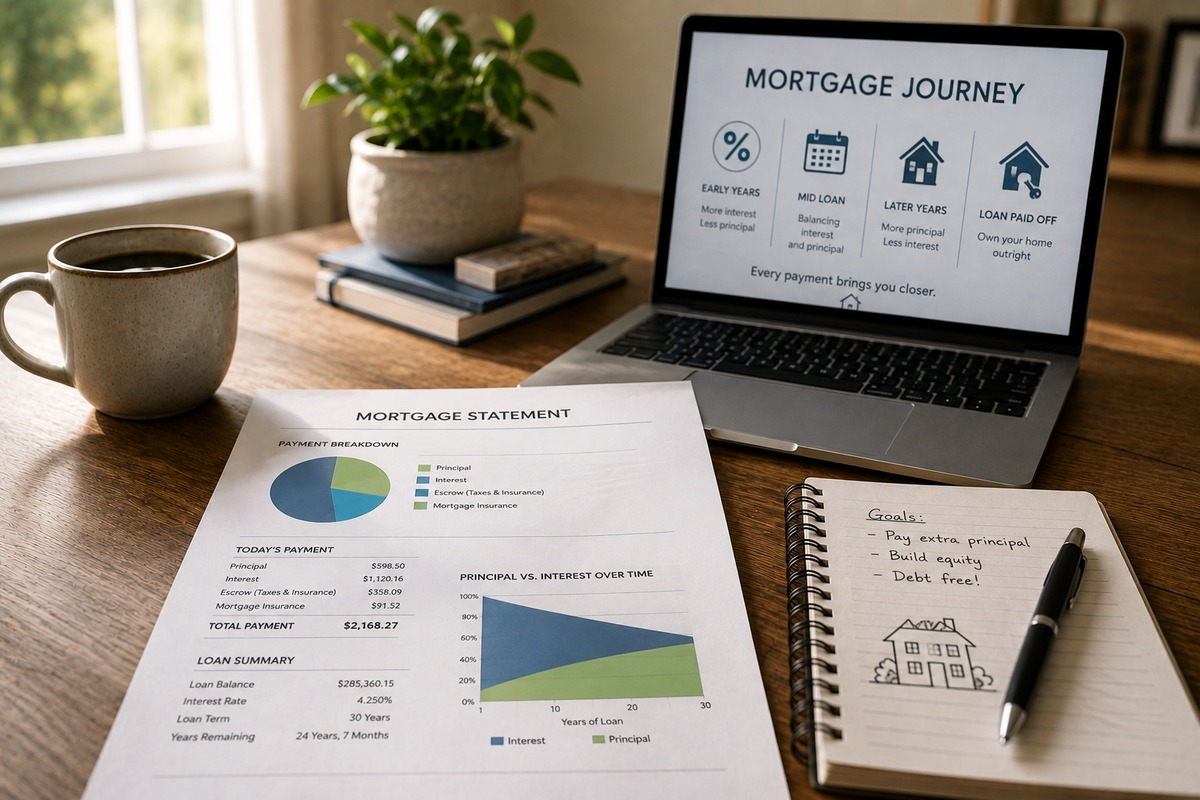
A mortgage payment may look consistent from month to month, but the way that payment works changes throughout the life of the loan. Understanding how principal, interest, escrow, and other costs evolve can help homeowners read statements more confidently and see the progress they are making over time.

Principal and Interest Shift Over Time

With a typical fixed-rate amortizing mortgage, the combined principal-and-interest payment remains the same. Early in the loan, a larger portion generally goes toward interest because the outstanding balance is higher. As the balance declines, more of each payment is applied to principal.

Escrow Can Change the Total Payment

Property taxes and homeowners insurance are separate from the fixed interest rate. If these expenses are collected through escrow, changes in tax bills, insurance premiums, or escrow shortages can increase or decrease the total monthly payment even when principal and interest remain stable.

Mortgage Insurance May Eventually End

Some borrowers pay mortgage insurance based on their loan type and down payment. Depending on the program and applicable rules, this cost may be eligible for cancellation after certain requirements are met, while other forms may remain for the life of the loan unless the mortgage is refinanced.

Extra Payments Affect the Timeline

Additional principal payments can reduce the outstanding balance and shorten the payoff period when applied correctly. They generally do not automatically change the scheduled monthly payment, but they may reduce the total interest paid over the life of the loan. Homeowners should confirm how their servicer applies extra funds.

Your mortgage is not static, even when the interest rate is fixed. The balance declines, the principal-and-interest mix changes, and taxes, insurance, or mortgage insurance may alter the total payment. Reviewing your statements regularly helps you understand these changes and track your progress toward owning the home outright.
Filed Under: Mortgage Tips Tagged With: Amortization, Homeownership, Mortgage Tips

Understanding Mortgage Servicing After Closing

August 12, 2026 by Regine Lane

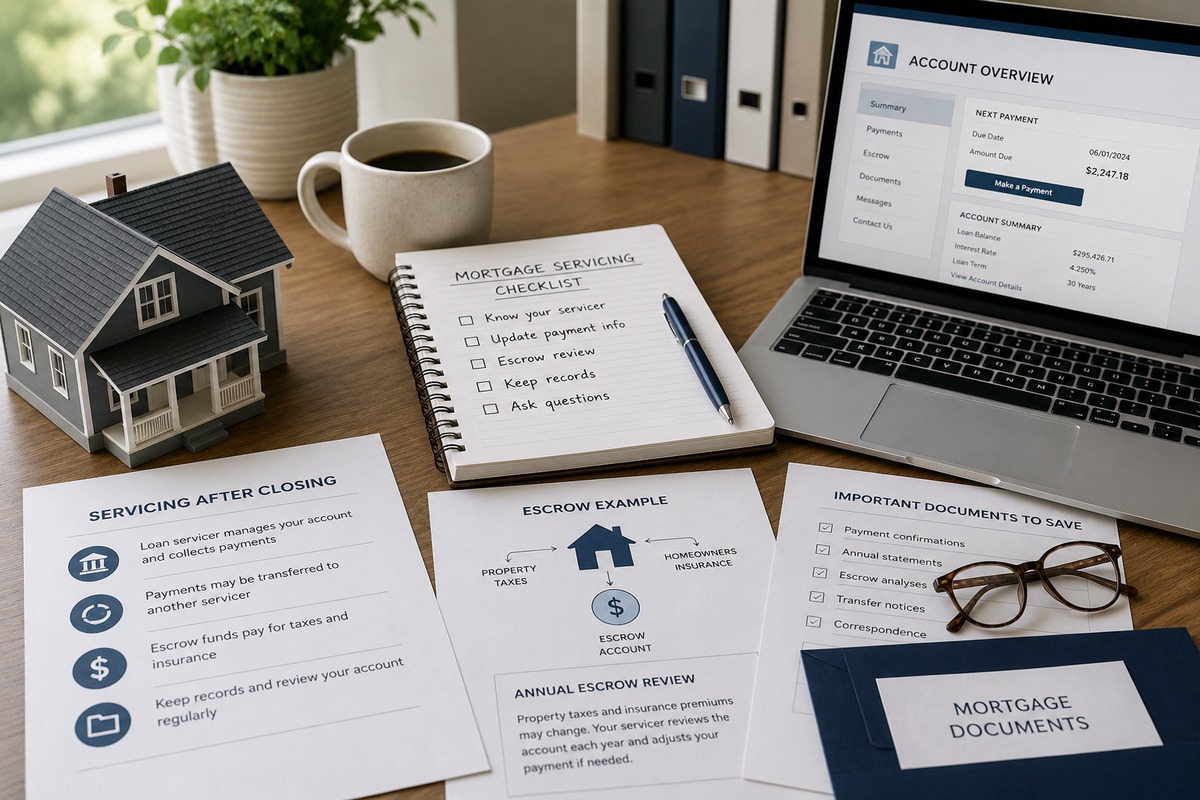
Closing day marks the end of the home-buying transaction, but it also begins the long-term process of managing your mortgage. After closing, a mortgage servicer becomes responsible for collecting payments, maintaining account records, managing escrow when applicable, and answering questions about your loan. Understanding the servicer’s role can help you avoid confusion and manage your mortgage with confidence.

Know the Difference Between a Lender and a Servicer

The company that originated your mortgage may not be the company that manages it afterward. Your lender provided the financing, while your servicer handles the day-to-day administration of the loan. In some cases they are the same company, but mortgage servicing rights may also be transferred.

Watch for Transfer Notices

If your loan is transferred, you should receive notices explaining when the change takes effect, where future payments should be sent, and how to contact the new servicer. A servicing transfer does not change your interest rate, loan balance, or other core terms. Review all notices carefully and update automatic payments when necessary.

Understand Escrow and Annual Reviews

If your payment includes an escrow account, the servicer collects funds for property taxes and homeowners insurance and pays those bills when due. The account is typically reviewed each year. Changes in taxes, insurance, or the escrow balance may cause your total monthly payment to increase or decrease.

Keep Records and Ask Questions

Save payment confirmations, annual statements, escrow analyses, and transfer notices. Review your account regularly and contact the servicer promptly if a payment is missing, a balance appears incorrect, or you receive an unfamiliar notice. Early communication can prevent small issues from becoming larger problems.

Mortgage servicing is the ongoing administrative side of your home loan. Knowing who manages your account, how transfers work, and how escrow affects your payment can make the years after closing much easier to navigate.

Filed Under: Mortgage Tips Tagged With: Homeownership, Mortgage Servicing, Mortgage Tips

  • « Previous Page
  • 1
  • …
  • 3
  • 4
  • 5
  • 6
  • 7
  • …
  • 22
  • Next Page »

Envision Funding
Private Money Lender
Call Today: 678-719-9669

Connect with Us!

Let’s Keep In Touch!

  • This field is for validation purposes and should be left unchanged.

Browse Articles by Category

The Latest Articles

  • Why a Condo’s Finances Can Matter Almost as Much as Yours When Getting a Mortgage
  • What Happens When the House You Want Has a Solar Loan Attached to It?
  • Could Paying Off a Debt Before Applying for a Mortgage Actually Be the Wrong Move?
  • Why Your First Mortgage Payment Might Be Farther Away Than You Expect
nmlsconsumeraccess.org
Equal Housing Lender

Envision Funding Solutions, Real Estate Loans, Kennesaw, GA

Our Location

Envision Funding Solutions LLC
3104 Creekside Village Dr, Ste 507 Kennesaw, GA 30144

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in