Envision Funding

We Close Loans Fast!

  • Home
  • About
    • About Us
    • Privacy Policy
  • Blog
  • Resources
    • First Time Home Buyer Tips
    • First Time Home Seller Tips
    • Closing Costs
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage FAQ
    • Mortgage Glossary
    • Debt Solutions
  • Applications
    • Apply Now Short Form
    • Business Funding Full Application
    • Broker Registration
    • Real Estate Lending Quick Application
  • Loan Programs
    • Business Loans
    • Commercial Loans
  • Contact

How a Solar Panel Lease Can Complicate a Home Purchase

November 13, 2026 by Regine Lane

Solar panels can be an appealing feature when you are shopping for a home. They may help offset electricity costs, and many buyers like the idea of producing energy on-site. But there is an important difference between buying a house with solar panels that are owned outright and buying one with panels covered by a lease or another financing agreement.

That difference can matter during mortgage approval and long after closing.

Start With Who Owns the Panels

Some homeowners purchase their solar systems outright. Others finance the equipment with a loan, sign a solar lease, or enter into a power purchase agreement under which they pay for the electricity generated. These arrangements can create different payment obligations and responsibilities for maintenance, repairs, and equipment removal.

Do not assume the panels are included in the home sale simply because they are attached to the roof. Ask the seller for the complete solar agreement and any related loan documents before you make a final decision.

Why Your Lender Needs the Details

A lender may need to determine whether the solar equipment is owned, leased, or subject to a lien or other recorded interest. The agreement can affect how the property is valued, what obligations transfer to the buyer, and whether the financing arrangement meets the loan program’s requirements.

If the buyer must assume a monthly solar payment, that obligation may also need to be considered during mortgage qualification, depending on the loan type and agreement. A solar company may require its own approval before a lease or contract can be transferred. These steps can take time, so discovering the arrangement shortly before closing is rarely ideal.

Look Beyond the Monthly Payment

Ask how long the agreement lasts, whether payments increase over time, who maintains the panels, and what happens if the roof needs replacement. Find out whether the contract can be transferred to a new owner, bought out, or terminated, and what each option costs. Review whether the seller is responsible for paying off any balance before closing.

You should also compare recent utility bills with the solar payments to understand the home’s actual energy expenses. Savings advertised in a listing may not match your future usage or the terms you will inherit.

Get the Documents Early

Share the solar paperwork with your lender, real estate agent, and title or closing professional as soon as possible. If you have questions about contract obligations, consider seeking advice from an appropriate legal professional. A solar system does not automatically make a home difficult to finance, but an unclear agreement can create delays.

The goal is simple: know exactly what comes with the home, what you will owe, and what your mortgage lender needs before you commit.
Filed Under: Mortgage Tips Tagged With: Mortgage Tips, Solar Lease, Solar Panels

Why a Property Line Encroachment Can Affect Your Mortgage Approval

November 10, 2026 by Regine Lane

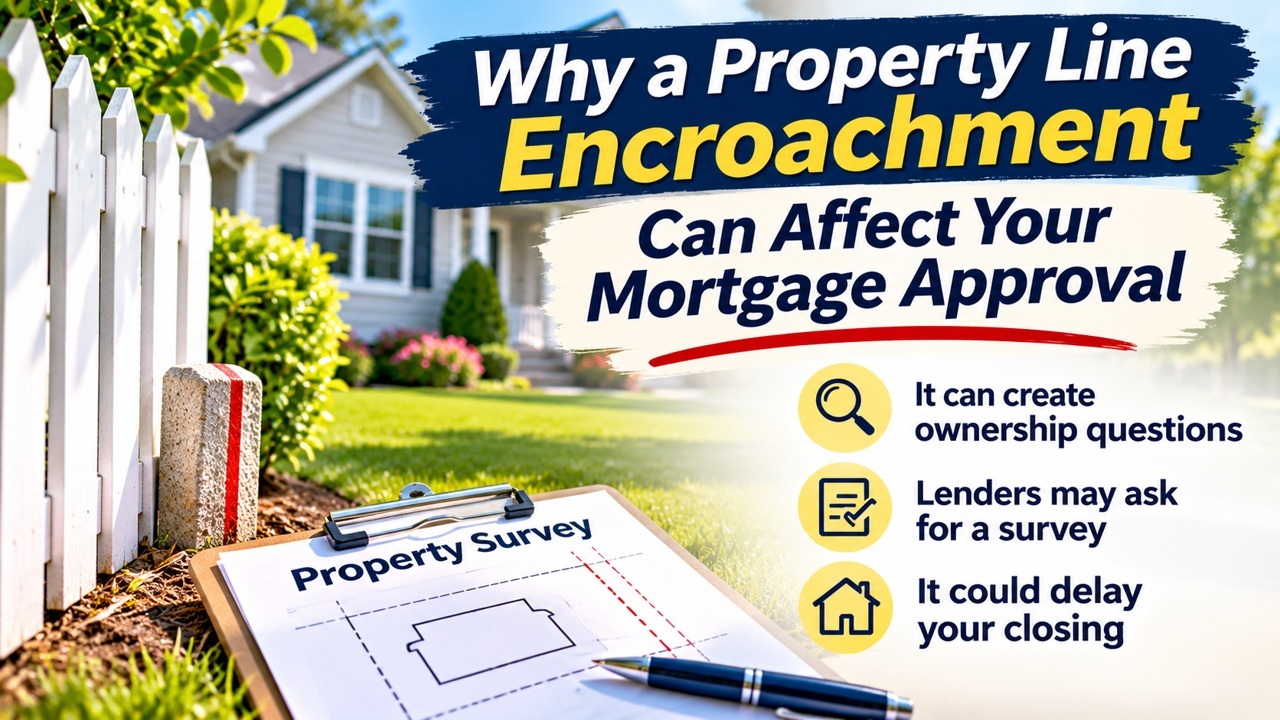
A backyard fence, detached shed, or concrete patio may seem like a straightforward feature of a home. But what happens when part of that structure crosses the legal property line? Buyers sometimes discover this issue during the title or survey review, just as they are preparing to close. Known as an encroachment, it can raise questions that go beyond neighborly disagreements and may affect the mortgage process.

What Is an Encroachment?

An encroachment occurs when a structure or improvement extends onto land owned by someone else. Common examples include a fence installed several feet over the boundary, a driveway that overlaps an adjacent parcel, or a shed built partly on a neighbor’s lot. The opposite can happen too: a neighbor’s structure may extend onto the property you plan to buy.

Not every apparent boundary issue is an actual encroachment. Landscaping, old fence lines, and informal neighborhood arrangements can make property boundaries difficult to judge by sight alone. A survey and the recorded property description can help clarify what is happening.

Why It Can Matter to a Lender

A mortgage lender wants to understand whether the property offers acceptable security for the loan. A significant encroachment may affect the property’s marketability, value, or the owner’s ability to use part of the land. Title insurers may also need to determine whether they can provide the coverage required by the lender.

The seriousness depends on the facts. A small fence issue may be treated differently from a garage that extends onto another parcel. The location of the improvement, local rules, loan program, and available documentation all matter. An encroachment does not automatically make a home ineligible for financing, but it may prompt additional review.

What Buyers Should Ask

If a survey or title report identifies a possible encroachment, ask your real estate agent and title professional to explain exactly where it is and what documents exist. Find out whether the parties have a recorded agreement, easement, boundary adjustment, or another legally recognized solution. Ask the lender whether the issue needs to be resolved before closing.

Avoid relying solely on a seller’s assurance that the neighbors have never complained. A friendly arrangement today may not answer questions about future ownership or resale. Depending on the situation, a real estate attorney or licensed surveyor may need to help determine the next step.

The best time to uncover a boundary problem is before the final days of a transaction. Reviewing the available records early can help buyers understand the risk, evaluate possible solutions, and keep an unexpected property line issue from becoming a last-minute mortgage surprise.

Filed Under: Mortgage Tips Tagged With: Mortgage Approvals, Mortgage Tips, Property Lines

  • 1
  • 2
  • 3
  • …
  • 135
  • Next Page »

Envision Funding
Private Money Lender
Call Today: 678-719-9669

Connect with Us!

Let’s Keep In Touch!

  • This field is for validation purposes and should be left unchanged.

Browse Articles by Category

The Latest Articles

  • How a Solar Panel Lease Can Complicate a Home Purchase
  • Why an Unpermitted Garage Conversion Can Affect Your Mortgage
  • Veterans Day: Honoring Those Who Served and Helping Veterans Feel at Home
  • Veterans Day: Honoring Service and Understanding VA Home Loan Benefits
nmlsconsumeraccess.org
Equal Housing Lender

Envision Funding Solutions, Real Estate Loans, Kennesaw, GA

Our Location

Envision Funding Solutions LLC
3104 Creekside Village Dr, Ste 507 Kennesaw, GA 30144

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in