Envision Funding

We Close Loans Fast!

  • Home
  • About
    • About Us
    • Privacy Policy
  • Blog
  • Resources
    • First Time Home Buyer Tips
    • First Time Home Seller Tips
    • Closing Costs
    • Home Appraisal
    • Home Inspection
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Mortgage FAQ
    • Mortgage Glossary
    • Debt Solutions
  • Applications
    • Apply Now Short Form
    • Business Funding Full Application
    • Broker Registration
    • Real Estate Lending Quick Application
  • Loan Programs
    • Business Loans
    • Commercial Loans
  • Contact

Veterans Day: Honoring Those Who Served and Helping Veterans Feel at Home

November 11, 2026 by Regine Lane

Veterans Day is a time to recognize the men and women who have served in the United States Armed Forces. Their commitment deserves gratitude that extends beyond a single day. For real estate professionals and communities, one meaningful way to show appreciation is to help veterans and military families feel informed, welcomed, and supported when making housing decisions.

Housing Needs Can Be Different
Military life can involve frequent moves, deployments, changing duty stations, and long stretches away from family. A veteran transitioning to civilian life may be choosing a permanent neighborhood for the first time in years. Others may be downsizing, relocating closer to relatives, or searching for a home with accessibility features. There is no single veteran homebuyer experience, so listening carefully matters more than making assumptions.

Understanding the VA Loan Option
Some eligible veterans, active-duty service members, and surviving spouses may qualify for a home loan backed by the U.S. Department of Veterans Affairs. VA-backed purchase loans can offer benefits such as no required down payment for many qualified borrowers and no monthly private mortgage insurance. Eligibility, lender approval, property standards, closing costs, and possible funding fees still apply. Buyers should speak with an experienced lender to understand their individual options.

What Buyers Can Look For
Beyond financing, practical features can make a home easier to enjoy. Consider commute times, access to health services, neighborhood amenities, bedroom placement, entry steps, and maintenance needs. Some buyers value a quiet home office; others need flexible space for extended family. If accessibility is a priority, evaluate door widths, bathroom layouts, stairs, and the potential cost of modifications. The right home is one that supports the buyer’s actual daily routine.

How Communities Can Help
Real estate agents can provide clear explanations, avoid rushing major decisions, and connect clients with appropriate local resources. Neighbors can welcome new residents without assuming every veteran has the same needs or preferences. Appreciation is most meaningful when it is respectful, practical, and ongoing.

This Veterans Day, we honor the service and sacrifices of veterans and their families. Whether someone is buying a first home, returning to a familiar community, or beginning a new chapter, they deserve patience, accurate information, and the opportunity to find a place that truly feels like home.
Filed Under: Holidays Tagged With: Honor Our Veterans, Military Families, Veterans Day

Veterans Day: Honoring Service and Understanding VA Home Loan Benefits

November 11, 2026 by Regine Lane

Veterans Day is an opportunity to recognize the men and women who have served in the United States Armed Forces. Their commitment deserves gratitude that extends beyond a single day. For veterans, active-duty service members, and eligible surviving spouses who are considering homeownership, it is also a meaningful time to understand a benefit that may help them purchase or refinance a home: the VA home loan program.
What a VA Home Loan Does

A VA home loan is generally made by a private lender and backed by a guaranty from the U.S. Department of Veterans Affairs. The guaranty helps eligible borrowers access financing under terms that can differ from conventional mortgages. For many eligible buyers, a VA-backed purchase loan may offer a no-down-payment option, provided the sales price does not exceed the appraised value and the borrower meets lender requirements.

VA loans generally do not require monthly private mortgage insurance. That can make a difference when comparing monthly housing costs. However, a VA funding fee may apply, and certain borrowers qualify for an exemption. Closing costs, property taxes, homeowners insurance, and other expenses still need to be considered.

Eligibility Is the Starting Point

Military service alone does not automatically establish approval for a particular mortgage. Borrowers typically need a Certificate of Eligibility to confirm their VA loan benefit, and the lender reviews income, credit, debts, and the property. Service requirements and surviving-spouse eligibility rules can vary. A lender experienced with VA financing can help explain the steps and request the appropriate documentation.

The Property Matters Too

VA financing is intended for eligible residential use, and the property must meet applicable appraisal and minimum property requirements. An appraisal evaluates value and certain property conditions; it is not a substitute for a comprehensive home inspection. Buyers should still consider an independent inspection so they can understand the home’s condition before closing.

A Thoughtful Way to Explore the Benefit

If you are eligible and thinking about buying, start by asking a qualified lender for a comparison of VA and other available loan options. Look at the interest rate, estimated monthly payment, cash needed at closing, funding fee if applicable, and total borrowing costs. The right choice depends on your circumstances, not simply the loan label.

Today, we honor veterans and their families for their service and sacrifice. Understanding the benefits earned through that service is one practical way to support informed decisions about the next chapter of homeownership.

Filed Under: Mortgage Tagged With: Thank You Veterans, VA Home Loan, Veterans Day

Why a Property Line Encroachment Can Affect Your Mortgage Approval

November 10, 2026 by Regine Lane

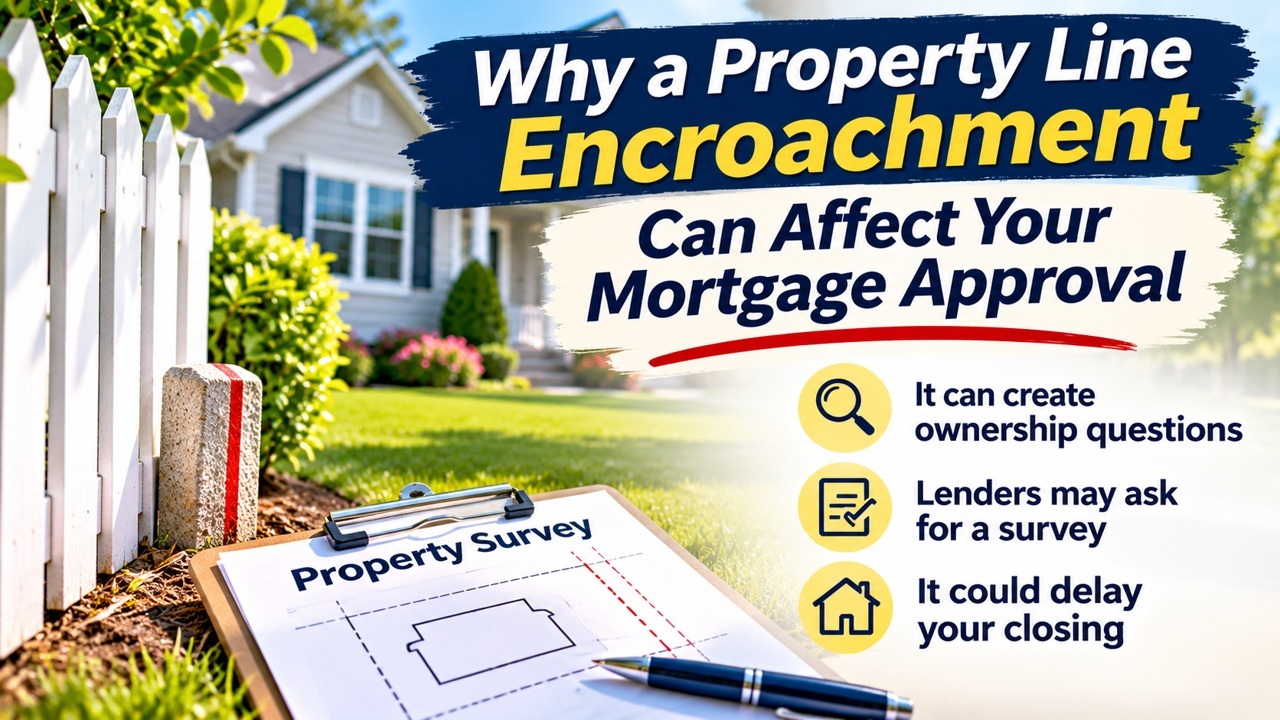
A backyard fence, detached shed, or concrete patio may seem like a straightforward feature of a home. But what happens when part of that structure crosses the legal property line? Buyers sometimes discover this issue during the title or survey review, just as they are preparing to close. Known as an encroachment, it can raise questions that go beyond neighborly disagreements and may affect the mortgage process.

What Is an Encroachment?

An encroachment occurs when a structure or improvement extends onto land owned by someone else. Common examples include a fence installed several feet over the boundary, a driveway that overlaps an adjacent parcel, or a shed built partly on a neighbor’s lot. The opposite can happen too: a neighbor’s structure may extend onto the property you plan to buy.

Not every apparent boundary issue is an actual encroachment. Landscaping, old fence lines, and informal neighborhood arrangements can make property boundaries difficult to judge by sight alone. A survey and the recorded property description can help clarify what is happening.

Why It Can Matter to a Lender

A mortgage lender wants to understand whether the property offers acceptable security for the loan. A significant encroachment may affect the property’s marketability, value, or the owner’s ability to use part of the land. Title insurers may also need to determine whether they can provide the coverage required by the lender.

The seriousness depends on the facts. A small fence issue may be treated differently from a garage that extends onto another parcel. The location of the improvement, local rules, loan program, and available documentation all matter. An encroachment does not automatically make a home ineligible for financing, but it may prompt additional review.

What Buyers Should Ask

If a survey or title report identifies a possible encroachment, ask your real estate agent and title professional to explain exactly where it is and what documents exist. Find out whether the parties have a recorded agreement, easement, boundary adjustment, or another legally recognized solution. Ask the lender whether the issue needs to be resolved before closing.

Avoid relying solely on a seller’s assurance that the neighbors have never complained. A friendly arrangement today may not answer questions about future ownership or resale. Depending on the situation, a real estate attorney or licensed surveyor may need to help determine the next step.

The best time to uncover a boundary problem is before the final days of a transaction. Reviewing the available records early can help buyers understand the risk, evaluate possible solutions, and keep an unexpected property line issue from becoming a last-minute mortgage surprise.

Filed Under: Mortgage Tips Tagged With: Mortgage Approvals, Mortgage Tips, Property Lines

  • 1
  • 2
  • 3
  • …
  • 675
  • Next Page »

Envision Funding
Private Money Lender
Call Today: 678-719-9669

Connect with Us!

Let’s Keep In Touch!

  • This field is for validation purposes and should be left unchanged.

Browse Articles by Category

The Latest Articles

  • Veterans Day: Honoring Those Who Served and Helping Veterans Feel at Home
  • Veterans Day: Honoring Service and Understanding VA Home Loan Benefits
  • Why a Property Line Encroachment Can Affect Your Mortgage Approval
  • What’s Ahead For Mortgage Rates This Week – November 9th, 2026
nmlsconsumeraccess.org
Equal Housing Lender

Envision Funding Solutions, Real Estate Loans, Kennesaw, GA

Our Location

Envision Funding Solutions LLC
3104 Creekside Village Dr, Ste 507 Kennesaw, GA 30144

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in